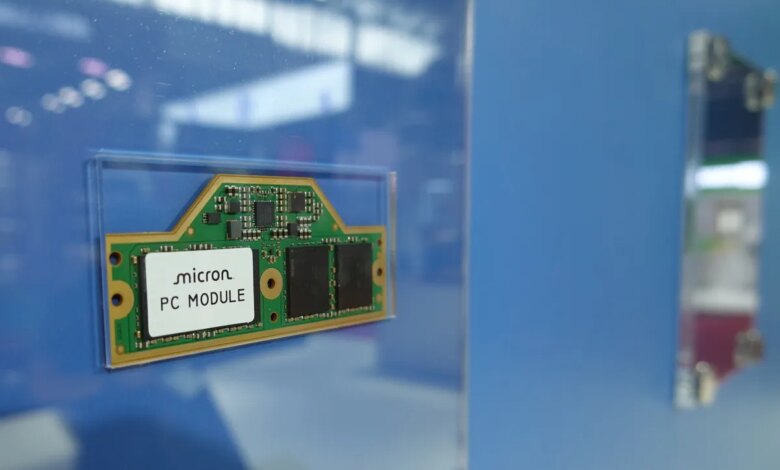
Micron Technology, located in Boise, Idaho, is currently captivating Wall Street. The sustainability of this newfound interest largely hinges on the duration of the supply shortage for memory chips driven by artificial intelligence (AI).
The company asserts that it has fortified its market position for the long haul, equipping itself to weather sudden shifts in demand or excess supply. This confidence has resonated on Wall Street, enabling Micron to briefly eclipse the market valuations of Meta and Tesla last Thursday before settling back to closely match them by Friday.
To elaborate, Micron finished Friday’s trading session with a market capitalization nearing $1.27 trillion, compared to Meta’s $1.39 trillion and Tesla’s $1.42 trillion. In just the past month, Micron’s stock has surged over 236%, closing at $1,132 per share—a remarkable rise considering it had languished below $100 a share until mid-2025.
This transformation is stunning for a company predominantly recognized for its memory cards, once essential for enhancing the storage capacities of PCs, smartphones, and other electronic devices.
Analysts are not concerned about its traditional product line. Micron is reaping the benefits from the increased demand for memory chips driven by the AI data center expansion, which has led to a shortage of both DRAM and NAND chips, especially High-Bandwidth Memory (HBM). The memory requirements for a single AI server far exceed those of a laptop.
Major AI system manufacturers like Nvidia, alongside large tech firms like Microsoft, Amazon AWS, Google, Meta, and Oracle, are consuming vast amounts of memory. This high demand is causing other companies, including PC manufacturers like Dell and HP, to stockpile memory as a protective measure.
This ongoing shortage, referred to as “RAMageddon,” is expected to last until 2027, contributing to rising prices for consumer electronics, including Apple devices and gaming consoles like Xbox.
As the tech sector clamors for more memory, Micron reported impressive earnings for the third quarter last week. Revenue surged year-on-year to $41.45 billion, while profits skyrocketed from $1.88 billion to $28.2 billion. The company also projected fourth-quarter revenues between $49 billion and $51 billion.
Wall Street’s enthusiasm has been fueled by a search for more AI-related companies with similar potential as Nvidia, increasing its admiration for Micron.
One historical issue for memory chip manufacturers like Micron and Samsung is that expanding production capabilities is both costly and time-consuming. Often, demand diminishes just as companies are able to ramp up production, leading to an excess supply and falling prices.
Micron proactively addressed potential concerns about an AI market downturn by establishing multiple long-term supply agreements, including those with Nvidia and the AI company Anthropic, which should provide stability. During its earnings presentation, Micron announced 16 strategic agreements across various sectors, including data centers, consumer electronics, and automotive, which are anticipated to significantly alter its operational model.
These moves have convinced several analysts that Micron is poised to be a long-term, profitable investment. In a research note, tech analyst Sebastien Naji from William Blair highlighted that the demand is consistently outpacing the capacity expansion of new cleanroom facilities.
“With the strong likelihood of continued average selling price (ASP) growth in the upcoming quarters and enhanced revenue visibility from an expanding array of long-term agreements, we foresee opportunities for sustained earnings growth and reaffirm our Outperform rating,” Naji stated.
Whether Micron can sustain this momentum long-term without experiencing a market downturn remains uncertain. However, for a fleeting moment on Thursday, this American company was valued more highly than some of the industry’s leading players.